
Following on from the announcement of the Wisk, SkyGrid and Insitu acquisition, Archer have followed up with their results for the second quarter which revealed a net loss of USD284.2m on revenues of USD5m. This compares with a loss of USD256.2m in Q1 and takes the net losses for the year to USD540.4. Cumulatively, the business has racked up deficit of USD2.784 billion.
Expressed as Adjusted Earnings Before Interest Taxation Depreciation and Amortisation (Adj EBITDA) the loss was USD177.1 million at the lower end for the range USD170m to USD200m forecasted in its Q1 shareholder letter. Looking ahead to Q3 the company again forecasts an Adj EBITDA loss in the range of USD170m to USD200m although the forecast was prepared before the Insitu acquisition which will have some impact on revenues.
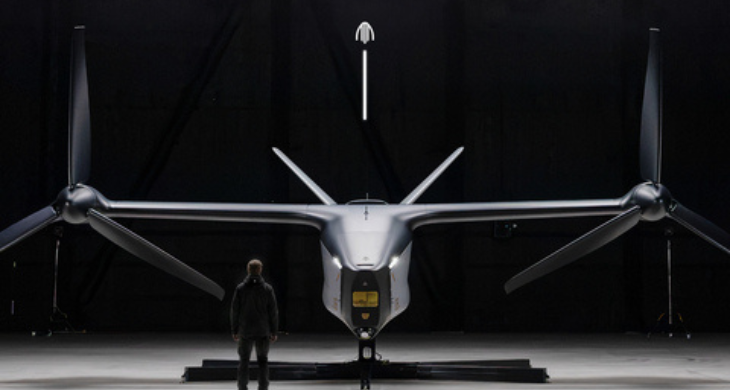
Interestingly, and perhaps tellingly the shareholder letter makes much of the recent acquisition and moves to develop an unmanned tilt rotor design hVTOL for both defence and civil applications with CEO Adam Goldstein quoted as saying “Today is an important inflection point for Archer. With the planned acquisitions of Wisk, Insitu, and SkyGrid from Boeing, coupled with our recent unveiling of Halo, ZEE, and ACES, we are rapidly advancing our diversified, multi-platform strategy across air taxis, UAS and AI to lead the next generation of aerospace and defence.” While making little mention of the troubled Midnight programme and no mention at all of the expected certification timetable for the eVTOL, normally a fixture of Archer shareholder letters and notably absent from this one.
In terms of reserves the company reports that it has cash, cash equivalents and short term investments of USD1.56bn compared with USD1.775.9bn at the close of Q1.
Image: Archer
