
BROUGHT TO YOU BY FLYING FINANCE
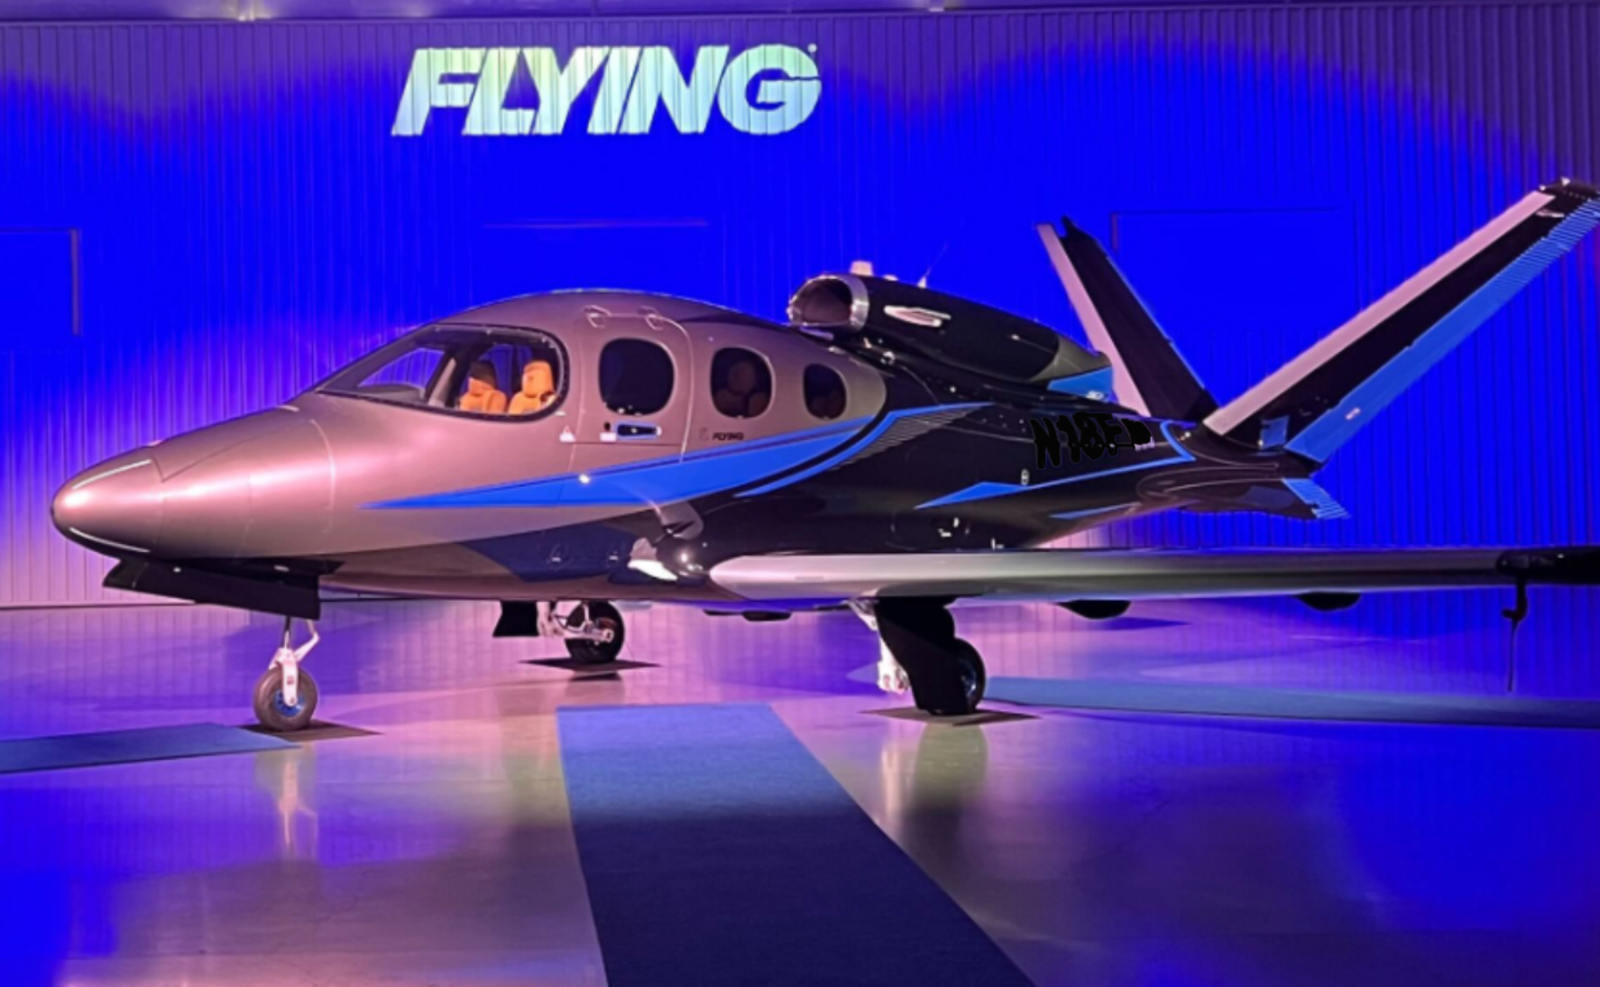
As I started writing this article in mid-October, the FLYING Finance countdown for year-end bonus depreciation sat at 77 days. I must step around the fact that Christmas is even closer and focus on a conversation I had earlier this year with the Daher TBM team in Fort Lauderdale, Florida.
As of June, the General Aviation Manufacturers Association (GAMA) shipment reports showed Daher had delivered 27 brand new TBM 980’s, not to mention nine Kodiak. According to one member of the TBM team, every single delivery he took part in was driven by one thing: bonus depreciation.
Often coming from the sale of a business or some other liquidity event, aircraft owners are able to stave off, or at least pare back, the impact of the tax man through a timely purchase and business use of an aircraft ahead of year-end. As a banker advising clients on business exits, these purchases would complement other strategies, like using donor advised funds, to maximize the value of the transaction for the owner.
While the average loan at FLYING Finance closes in around 39 days from application to delivery, that average has two sides—the 10-day closings and the pre-approvals where buyers are still shopping.
If you are in the market for year-end, waiting may mean you need everything to go just right, and if the prebuy does not go well, any squawks needing to be completed get bumped by the maintenance shop, or there are delays scheduling ferry pilots or CFIs, your year-end tax plan may stall.
If you are thinking about putting an airplane on the books in 2026, the calendar matters now more than it usually does. But the calendar is not the whole story, and the questions buyers ask FLYING Finance every day tell us most people are working through the same handful of decisions, deadline or not.
With hundreds of loans already closed this year, the questions we get at the outset are remarkably consistent: credit scores and loan terms, stepping up to turbine, the new MOSAIC light sport rules, older aircraft and valuation, and, increasingly as the year winds down, taxes. This article takes those questions in roughly the order people ask them, starting with the one that has a deadline attached to it.
Bonus Depreciation: Why Year-End Still Matters
The One Big Beautiful Bill Act, signed July 4, 2025, made 100 percent bonus depreciation permanent for qualifying property acquired after January 19, 2025. Before that law, bonus depreciation had been stepping down each year, twenty percent per year, phasing out from 2022. That phase out is gone and bonus depreciation at up to 100 percent is fully back.
So why does year-end still matter? Because the bonus depreciation deduction is taken in the tax year the aircraft is placed in service, not the year you sign a purchase agreement or the year you start shopping. If you want the deduction on your 2026 return to pare back profits for 2026, the airplane has to be bought, closed, delivered, and ready for business use by December 31. An airplane that closes on January 4 lands on your 2027 return instead.
There are specific aspects of the reinstated bonus depreciation that are more detailed and we cover them in more detail on our depreciation page. That said, business use must exceed 50 percent, so get that one business flight in before the ball drops. Personal flying, commuting, and entertainment flights generally do not count toward the bonus depreciation test, and you need logs to prove your business use. As pilots ourselves, our flight logs include date, entity involved if you have multiple dry leases, where to, the hours, nautical miles, passengers, and purpose. Purpose also helps answer the question around business purpose or business entertainment.
Outside the logs and delivery date, other influencing factors that come up when we hop on calls with our customers and their tax accountants include how the aircraft is owned, whether it is leased under a dry lease or a Part 135 certificate, how grouping election is structured, and whether passive activity rules apply. Even then, states do not all follow the federal rules. Several states decouple from federal bonus depreciation, so the state-level benefit may be smaller or spread over years. All that to say, allow time to get everything structured so that you, your attorney, and your CPA are all happy and in compliance.
If you have been on flyingfinance.com recently, you may have interacted with Amelia, our interactive tool trained for aviation. Amelia gets asked some version of “How much would I save on a $2 million turboprop at a 37 percent bracket?” often enough that I will answer the arithmetic: a full first-year deduction on $2 million at a 37 percent federal rate is worth up to $740,000 in federal tax, if every condition is met. That “if” is doing a lot of work. We finance airplanes; we do not give tax advice, and neither should anyone selling you one, so call your CPA or aviation tax attorney before you open escrow and schedule the prebuy inspection.
Working Backward From December 31
If the tax benefit is part of your reason to buy this year, the practical question is how long it takes to get from “I’m interested” to “it’s in service”. The answer is longer than most people expect, mostly because of steps that have nothing to do with the loan.
A realistic backward timeline looks like this. Closing and delivery need to happen by the middle of December, because title companies, escrow agents, and the FAA Registry slow down over the holidays and nobody wants to be wiring funds on December 30th. Before that, a pre-buy inspection typically takes one to two weeks, longer if the shop finds something that needs a decision. Before that, you need a signed purchase agreement on a specific aircraft you may still need to find. And before any of it, you should know what you can borrow so closing is a certainty.
Financing is the fastest part when started early. A pre-approval uses a soft credit pull that does not affect your score, and we typically return a decision in two business days. Once approved, your rate can be locked while you find the aircraft. A clean loan closes in 10 to 21 days. The buyers who miss year-end deadlines are almost never the ones who got pre-approved in October. They are the ones who found the perfect airplane on December 5 and started the paperwork that afternoon.
What Buyers Are Actually Asking
What rate can I get?
This is the most common question we hear, by a wide margin. As I write this, our published rates start in the mid-six percent range for jets, turboprops, and certified piston aircraft, with light sport and experimental aircraft priced somewhat higher. Interest rate spreads have been compressing this year as banks and credit unions awaited direction from the Federal Reserve.
That came as predicted, in September, when the Federal Reserve raised rates and gave indications rates could go higher. While the Fed chair and the Treasury secretary work towards a balance that will address the real sources of inflation in the services sector, we saw many lenders immediately increase rates and provide some relief to the compressed spreads. We expect interest rates will hold within about half of one percent for the near term.
That is the backstory. The actual rate on your aircraft loan depends on the aircraft, its mission, age, TTAF and hours to TBO, the loan amount and terms, and your credit profile. FLYING Finance covers these questions up front, pilot to pilot, so you know that the rate and terms provided in your approval from FLYING Finance are not just brochure terms after a skimmed over application.
What credit score do I need?
Close behind rates on the questions we receive is credit, usually phrased as “What score do I need for the best rate?” or “What can I expect with an 800 score?” Strong credit earns better pricing, but it is not a single-number decision.
For turbine aircraft, for example, lenders generally look for scores of 700 or higher, with the best pricing above 720, a debt-to-income ratio no higher than about 46 percent, and three to six months worth of payments in bank or brokerage accounts remaining after closing. For piston aircraft the bar is more forgiving, but the same factors still matter: income, existing debt, cash reserves, and flight experience all go into the picture. An 800 score with thin reserves can price worse than a 740 with a strong balance sheet.
We also look at what is actually factoring into the credit score. Recent late pays raise questions. A collection item from six years ago, less so. Real estate investors, particularly those on the residential side, often have lower credit scores when the investment mortgages are in their personal names. This and the debt ratios associated with those mortgages is why many AirBnB and traditional residential landlords ask the question “Should I Pay Cash for my Aircraft?“
What will my monthly payment be?
Buyers want a real number, and they should. Here is one we ran recently for a common question: a $480,000 Cirrus SR22 with 15 percent down is a $408,000 loan. At 6.22 percent over 20 years, the principal and interest payment is about $2,975 a month.
Shorten the term to 15 years and the payment rises to about $3,492, but you pay substantially less interest over the life of the loan. Scale that up to a $2 million turboprop with 15 percent down, and a $1.7 million loan at 6.36 percent over 20 years runs about $12,535 a month.
That payment is only part of owning an airplane. Insurance, hangar, annual, engine reserves, and fuel are real costs, and a lender will want to see that you can carry them.
How much do I need to put down?
For most certified aircraft including turbine aircraft with engines enrolled on a maintenance program and used under Part 91, plan on 15 percent down. For aircraft operated under Part 135, expect 20 percent or more.
The rule of thumb is that 15 percent has become standard when the aircraft has no cash flow attached to it. Once the aircraft loan payments are reliant on the aircraft generating sufficient cash flow, the risk steps up, usually with the hours, and the down payment follows. For non-recourse and light underwriting approaches like the low loan to value option we see quite a bit of for new Cirrus aircraft, 40 percent is standard.
Light sport aircraft are typically 15 percent, and experimental amateur-built aircraft range from 15 to 25 percent depending on the build and its documentation. For instance, a Van’s or Cubcrafters, while experimental, finances similarly to a certified taildragger like an Aviat or Cessna.
How long can I finance it?
Terms run up to 20 years for most aircraft. As most pilots know, the age of the airplane plays a smaller role than the hours on airframe and the time to overhaul. FLYING Finance regularly finances fifty and sixty year old Piper, Cessna, and Beechcraft aircraft where TTAF and the time to overhaul is reasonable.
There are certain parts that are time limited, such as the repack requirements on parachutes, or blades on helicopters, but in general, a well maintained aircraft may last and be financed generation after generation.
There are lenders, primarily regional and large banks, in the jet market that cap the aircraft’s age plus the loan term somewhere between 23 and 30 years. This is part of the reason you cannot walk into just any bank for aircraft loan.
Larger institutions opt to stay on the newer side of the market where repayment is more readily available if the borrower needs to refinance or sell the aircraft to payoff a loan. Some of the hardest loans to secure financing for are thirty year old mid size jets being put into service for charter. The hours are high, the lending pool is small and if the charter operation is not well heeled, the direct operating costs and maintenance expense do not support a viable business model.
Speaking of Part 135, these certificated aircraft are usually financed up to 15 years, with the up to ranging as low as five years. The age of the aircraft being chartered, the expected hours, maintenance milestones, and the cash flow considerations all come into play for this commercial underwriting.
Can I step up to a turboprop or jet?
Questions about turbine aircraft have grown steadily all year, often from pilots who have owned a piston single for years and are ready for more speed, range or cabin. FBO operators with locations at airports across the country, real estate investors with developments in different states, and business owners working to make the most of every day, are finding time and capacity through private aviation.
The financing for stepping up into the turbine markets works much the same way, with stronger requirements on credit, liquidity and aircraft maintenance (e.g. engine programs). Insurance underwriters are often the gate here more than lenders are. If you are moving into a turboprop or light jet, talk to an aviation insurance broker early about training requirements, because type ratings and CFI hours can drive your timeline as much as the loan. For pilots who are stepping up to a turboprop or light jet, but who are not planning to fly as PIC, both financing and insurance underwriters will want to know who will be flying the aircraft as pilot in command.
What about MOSAIC and the new light sport rules?
Interest in light sport aircraft has jumped with the FAA’s MOSAIC rule, which expands what qualifies as a light sport aircraft and what sport pilots can fly. Buyers are asking whether factory-built S-LSA under MOSAIC can be financed like certified aircraft.
In general, yes, with terms that reflect the category. Where the box has not changed is on the aircraft being known to the market. Lenders who might have to take back a plane are cognizant of the fact that unknown brands may have a very limited liquidation market, and finding comparables on brand new models, even for well known brands, is difficult right now. FLYING Finance takes a part in this, helping lenders understand which aircraft that may be EAB or LSA are gaining ground in the market, even before the used market for that model shapes up.
Can you finance an older airplane? What is it worth?
As touched on earlier, this is largely driven by the segment (piston, turboprop, jet aircraft) and the mission. Much of the general aviation fleet is decades old, hailing back to the golden era of aviation, and a mid 1960’s Cherokee Piper or a 1970’s Cessna 182 is still highly sought after.
Because of the activity in the market for older vintages, used aircraft can often be financed very similarly to new aircraft, but the appraisal, logbooks and maintenance history carry more weight. There are risks when aircraft has been a hangar queen or spent time in South America with missing logs. Lenders may be more insistent on squawks being completed than the buyers themselves. If you find an aircraft that has damage history, like using our Aircraft History Lookup tool, the plane may still be able to be financed, but having that discussion early will save everyone time and headache.
A 10- to 15-year-old Piper M Class, Pilatus PC-12, or Cirrus SR series may be the smoothest transactions we see, as all three are highly desirable aircraft recently beyond their maintenance milestones, and if the hours and the credit profile of the buyer match up, fifteen to twenty year financing can be secured in days.
Can I use the airplane for a flight school or leaseback?
We hear this often from buyers who want the aircraft to help pay for itself. Leaseback arrangements can offset ownership costs and can support business-use requirements for tax purposes, but they change the insurance, the maintenance load and sometimes the loan terms more significantly than a turboprop or light jet being certificated for light charter activity.
Leasebacks for Cirrus and Diamond aircraft are more readily financed than the Grumman Tiger we closed recently, in part because a flight school is less likely to teach initial lessons in an SR20 or DA40, so the risks of a stall off rotation or a rough landing is reduced somewhat. Overall, leaseback financing is seasonal, and many lenders who may finance an aircraft for leaseback in the first half of the year, move out of that airspace by mid to late summer.
The Market Right Now
The used piston market remains active and the turbine market that was previously a jet dominated story now has turboprops in the mix as well as year-end buying is peaking. Many jets that rolled off the production line two or three years ago are now selling for ten to fifteen percent more than the original price. Part of this is that inventory of well-equipped, low-time aircraft is still tight, below the historical average, and that means good airplanes sell quickly. This is another reason to have ownership structure and financing lined up before you start making offers. A pre-approval letter makes you a more credible buyer, and in a competitive deal where other interested parties include cash buyers, being able to show proof you can close is worth something to the seller.
What Matters All Year Around
Strip away the deadline and the advice is the same in April as it is in December. Get pre-approved before you shop, so you know your budget and can move when the right airplane appears.
Never skip the pre-buy inspection, no matter how good the logbooks look. Get an insurance quote early, especially if you are stepping up in performance (you can bind it in the days leading up to closing). Build a realistic ownership budget that goes well beyond the monthly payment. And if taxes are part of the reason you are buying, bring your tax adviser in at the beginning, not after the airplane is in the hangar.
The year-end clock is real, and for some of the more than one hundred buyers we are actively working with, it is a meaningful reason to act now. But the airplane should be the right airplane first. The tax benefit is a bonus, not the mission.
If you want to see where you stand, you can check today’s rates and get a soft-pull pre-approval at flyingfinance.com in a few minutes. Amelia is there around the clock to answer the questions above, and our team is here for the ones she cannot.
Tax information in this article is general and is not tax advice. Consult a qualified tax professional about your situation.
