
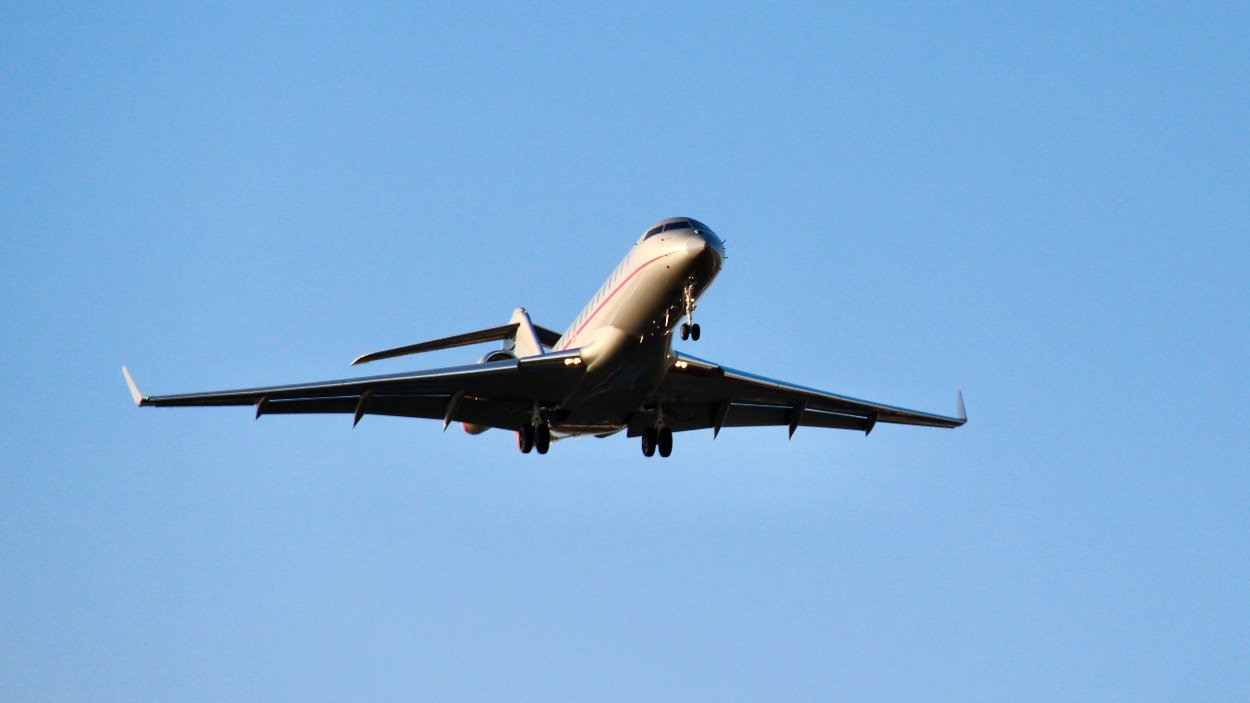
The business aviation market is not technically booming, but it remains healthier than its historical averages. Global Jet Capital’s Q2 2026 Market Brief points to growing flight activity, expanding OEM backlogs, tightening young-aircraft inventory and strengthening values. All of it points to a market holding steady into the second half of 2026.What the Q2 brief actually showsGlobal Jet Capital reported that year-to-date transaction dollar volume was lower in H1 of 2026, dropping 4.8% compared to the same period in 2025. Global Jet Capital notes that a significant portion of the decline may reflect delays in official data reporting rather than a real drop in activity. In Q2 2026, aircraft availability dropped from 6.7% in Q1 to 6.6%. Both percentages are lower than Q2 2025’s 7.3% and the historical average of approximately 10%.Despite this, business jet listings increased 3.3% year over year, driven mainly by listings for older aircraft, and global GDP grew 2.3% in Q2. Additionally, business jet departures increased 3.4% over the first half, led by fractional operators. OEM backlogs reached $66.8 billion, up 20.4% year over year. Global Jet Capital reported that aircraft bluebook values for like-aged aircraft in the second quarter increased 2.9% compared to the same quarter in 2025.Why the fundamentals still point upSeveral indicators are pointing in the same direction: global GDP continues to grow, and business jet departures have increased as the fractional user segment remained the strongest performer. At the same time, manufacturers continue reporting healthy order books, producing backlogs that exceed delivery growth. The report shows that flexibility, productivity and convenience are all contributing factors to the health of the market.Why it mattersGlobal Jet Capital notes that overall listings increased because older aircraft entered the market. Without looking closely, it might appear that supply is improving, but the inventory added isn’t necessarily the inventory buyers want most. Listings of aircraft aged 12 years and younger dropped, causing inventory within the most desirable segment to tighten further. Declining younger-aircraft supply supports residual values and makes replacement aircraft harder to source. Older aircraft meanwhile are heading in the opposite direction as they contribute to the growing inventory tally.Demand is strong enough to hold values up, keep young-aircraft inventory tight, and push OEM backlogs higher, with conditions balanced enough to keep the market from overheating. If newer used inventory keeps shrinking while backlogs and flight activity climb, 2027 may be the year buyers take a second look at aircraft that first flew before any of us had heard of the ice bucket challenge.Browse current business jet listings on GlobalAir.com
Trending
- This 2020 Cirrus SF50 G2+ Vision Jet Is an Ultra-Modern ‘AircraftForSale’ Top Pick
- The Black Hawk’s Role in Wildfire Response
- REVIEW: INTAMSYS Funmat Pro 310 NEO Pairs IDEX Precision With a 100°C Chamber for Engineering Polymers
- airBaltic employees brace for hundreds of job cuts
- APOD: 2026 October 5 – M104: The Sombrero Galaxy’s Tidal Streams
- Agile Space Industries Strengthens Board and Corporate Development to Support Continued Growth
- Second Dassault Falcon 10X joins flight tests with certification pushed to 2029
- Germany Backs Quantum Systems Deal For Ukraine
