
Affordable printers are taking on production work. Josef Prusa argues that the companies supplying them face a contest increasingly shaped by finance, software, IP and strategic information protection, and procurement, with consequences for everyone using the machines.
Join manufacturing technology experts at AMA: Software 2026 this week. Registration is free.
Josef Prusa’s concern is that Western countries will recognise the strategic value of desktop 3D printing after they have lost the companies capable of supplying it at scale.
“I would say this is like one minute to midnight,” he tells me.
The founder of Prusa Research believes established manufacturers have underestimated how far inexpensive machines have advanced, and how quickly that progress could change their own businesses. His assessment of some incumbents is blunt: “Many big and old players are in complete denial.” Prusa has a direct commercial interest in this argument. His company competes with the Chinese manufacturers whose growing influence concerns him.
In February, my Six Fault Lines analysis examined how sovereignty, production qualification, software power and financial pressure could reshape additive manufacturing. The accompanying Institutional Filters framework asked what allows a technically capable business to survive the requirements imposed by customers, investors and public institutions.
Prusa’s interview brings those questions to the desktop market, where the usefulness of the equipment and the future of its suppliers can look quite different.
He objects to “desktop” and “entry-level” being used as shorthand for limited capability.
“The printers in that bracket are so bloody damn good that they are consuming the lower tiers of the industrial,” he says.
He’s less absolute than that line suggests – an inexpensive machine cannot accommodate every build size or process every demanding material. His argument concerns the work that falls within its capabilities, and the growing number of customers discovering that a simpler process or material is sufficient.
“They want the repeatability and for it to be always the same,” Prusa says of customers’ priorities. Production requires more than a satisfactory print.
The available market figures require a qualification to Prusa’s assertion during our conversation that only desktop printing is growing. CONTEXT’s July report puts Q1 2026 entry-level shipments up 39% year on year and industrial shipments up 18%. Professional systems fell 22%. The analyst also describes entry-level machines taking demand from more expensive material-extrusion systems.
The pressure on the middle of the market is visible. So is growth at the high end. These are equipment price categories, rather than a direct measure of the value or sophistication of the work being performed.

Prusa is particularly concerned about what happens to a supplier’s ability to improve while that competition intensifies. “It doesn’t mean that the companies go under right away,” he says. “It slims their margins, so it is like slow suffocation.”
Margin compression here is cumulative, not sudden. A company can continue selling machines while losing the financial capacity to prepare the next generation. By the time a competitor’s difficulty becomes visible as an exit, the investment decisions that contributed to it may be years old.
Prusa attributes much of this pressure to state support for Chinese competitors, pointing to financing and tax advantages. He says his company has spent three years researching the issue: “I have the receipts.” He argues that telling European manufacturers to innovate faster ignores the resources required.
Asked to identify the support with the clearest competitive effect, Prusa points to a combination of tax deductions, grants, financing and other advantages rather than a single programme. He supplied Creality’s draft Hong Kong listing document as evidence.
The filing records government grants of RMB 34.6 million (USD 5.1m) in 2023, RMB 10.1 million (USD 1.5 m) in 2024, and RMB 16.3 million (USD 2.4m) in 2025. It also reports VAT refunds, additional VAT deductions and preferential corporate income-tax rates for qualifying entities. Its accounting notes describe a deduction equal to 200% of qualifying research and development expenditure when calculating taxable profits.
These disclosures substantiate the existence of public support for a major competitor. They do not establish how much that support reduced printer prices, or its contribution relative to product design, purchasing scale, manufacturing efficiency and margins.
Prusa’s concerns extend to the software that operates the machines and the designs it handles. “3D printers are concentrated in the places where a new IP is created,” Prusa says. “You have them at universities. You have them at engineering offices.”
Before a product is announced or a patent filed, a printer in development may already be handling the design that matters most. That makes the path of a design file, and the permissions attached to the systems handling it, relevant to the purchasing decision.
Prusa’s concerns combine technical access with the legal jurisdiction governing a supplier and its data. He argues that a reassuring account of a product’s security does not, by itself, resolve every question about who could ultimately require access.
The practical questions are specific. What information leaves the installation? Which functions require an external service? Who controls updates and administrative access? Can the customer continue operating if a service disappears, or move its work to another system?

Bambu Lab’s public position supplies material against which to assess those questions. In a 2 September security update, the company described its security and privacy certifications, a public security-update page and an expanded bug-bounty programme. An earlier Farm Manager case study described a customer managing machines on a local network without cloud dependence.
Whether that’s sufficient depends on the installation. A local workflow addresses the design-file question while leaving maintenance and long-term support unanswered. The same examination should apply to Prusa’s products. A claim to offer greater control is most useful when a customer can establish exactly what it can inspect, disable, maintain or replace. The interview does not provide independently verifiable evidence of a specific data-theft incident.
Asked what European buyers or policymakers should change over the next year, Prusa recommends bringing cybersecurity teams directly into printer procurement. “I recommend that every company’s cybersecurity department review the risks of 3D printing and adjust their procurement rules accordingly,” he says. He advocates the same review by states and their cybersecurity agencies, particularly for defence, publicly funded universities and critical infrastructure.
Some public buyers are answering part of that question through procurement law.
Section 849 of the FY2026 US defence authorisation introduces a restriction, beginning on 18 December 2026, on new Department of Defense procurement contracts for covered additive-manufacturing machines. The legislation defines an additive-manufacturing machine as integrated hardware and software, and extends the covered-machine definition to related equipment and services supplied by covered companies.
Coverage depends on specified company and jurisdictional criteria, with defined exceptions. The provision concerns defence procurement; it does not establish a general consumer sales ban or require every existing printer to stop operating. Technical performance and price no longer fully explain eligibility for those purchases; the supplier’s identity and status now do too.
Patents introduce another constraint on what a supplier can bring to market.
Prusa describes the discouragement of researching a possible product and finding that “every path is closed down by bogus patents”. The wording is his characterisation of the problem. His underlying concern is the cost and time required to challenge rights a company believes should never have been granted.
In his follow-up, Prusa identified two Anycubic filings concerning a filament-conveying device: US20250144881A1, a US patent application published in May 2025, and the German utility model DE202024100001U1, published in February 2024. In a July 2025 article, he alleged that the design copied the multiplexer used in Prusa’s MMU1, which he dates to 2016. His response identifies the disputed filings but does not provide the requested comparison between specific claims and dated prior-art documents. Anycubic was invited to respond, but as of publication date, a reply addressing the patent filings has not been received.
It doesn’t take a lost lawsuit to kill a product; the prospect of one is often enough.
September’s Stratasys-Bambu litigation illustrates how consequential patent rights have become across this market. A federal jury in Texas awarded Stratasys approximately $27.6 million in past damages after finding infringement of four patents. Bambu disagrees with the verdict and has said it intends to seek post-trial review and appeal. The wider dispute remains ongoing.
The case cuts against a clean East-vs-West story, and so does the fact that Bambu already won the European round of this same dispute earlier this year. Here, an established Western manufacturer is enforcing patents against a Chinese competitor. The merits of those rights require examination in their own terms; the verdict does not validate Prusa’s separate complaints about other patents.
Prusa’s account of European manufacturing supplies a different explanation for competitive difficulty, and a more practical starting point for a response.
“We are industrial countries, but set up for automotive,” he says of Czechia and Germany. “You are working for a year on the part, and then you have a three-year commitment.” That arrangement can serve an automotive programme well. It can fit a small hardware company poorly when the product changes rapidly and its entire market may amount to a modest annual order.
In Prusa’s account, a niche product selling 20,000 units can support a business while remaining an unappealing proposition for a supplier facing substantial setup work. A global customer base does not automatically produce the volumes or continuity that make conventional tooling attractive.
His description of China’s advantage in this setting is straightforward: “The speed gave the companies the edge.” Speed, not just cost, is the edge Prusa credits; and it’s the one thing a change in procurement rules can’t manufacture.
My reporting at Huafast in Shenzhen offered a practical example of desktop equipment organised around production. Its founder described typical industrial orders of 500 to 1,000 parts, while the visit showed the work surrounding the printers: materials handling, processing, packing and dispatch.
Prusa argues that improvements in printing are expanding the range of products that can be made without committing to a mold.
For his own company, he says, it becomes worth considering injection moulding “when we know that we will make more than 60,000 pieces of that certain part”.
A published example supplied by Prusa shows how those decisions work in practice. For the MK4S printer’s LCD display case, the company puts mould tooling at approximately €6,000 and the moulded part at €0.18, compared with €0.25 for printing or €0.32 including post-processing. On those figures alone, tooling is recovered after roughly 43,000–86,000 parts, depending on which printing cost is used.
The example supports the broader argument that printing can remain competitive into tens of thousands of units, rather than establishing a fixed 60,000-part threshold. The publication does not specify the production period for this comparison and acknowledges that a complete calculation requires costs including equipment, downtime, labour and electricity. It also identifies an operational reason for switching: printing the relatively large display cases was creating a bottleneck, while their established design reduced the need for further revisions.
A credible European response would have to make that possibility easier to realise. Equipment supply, production knowledge, accessible services and responsive component manufacturers all contribute. Preserving a 3D printer manufacturer matters most when it preserves something customers can actually use.
Prusa returns to that idea when describing the impact he wants the technology to have.
“I can easily put a printer, which is almost as good with some limitations on every engineer’s desk,” he says. Specialist systems retain capabilities that an inexpensive printer cannot reproduce. Yet broader access to equipment that is sufficient for the task can change who gets to experiment, how often a design is tested and how quickly a useful part is made.
The test for his argument, and for the response he advocates, is whether the industry can keep expanding that access while maintaining suppliers that customers can afford, rely on and meaningfully choose between.
Register now for AMA: Software 2026. Join 3D Printing Industry on 22 October for expert presentations, panel discussions and live audience Q&A exploring the software shaping additive manufacturing. Register here.
To stay up to date with the latest 3D printing news, don’t forget to subscribe to the 3D Printing Industry newsletter or follow us on LinkedIn.
Explore the full Future of 3D Printing and Executive Survey series from 3D Printing Industry, featuring perspectives from CEOs, engineers, and industry leaders on the industrialization of additive manufacturing, 3D printing industry trends 2026, qualification, supply chains, and additive manufacturing industry analysis.
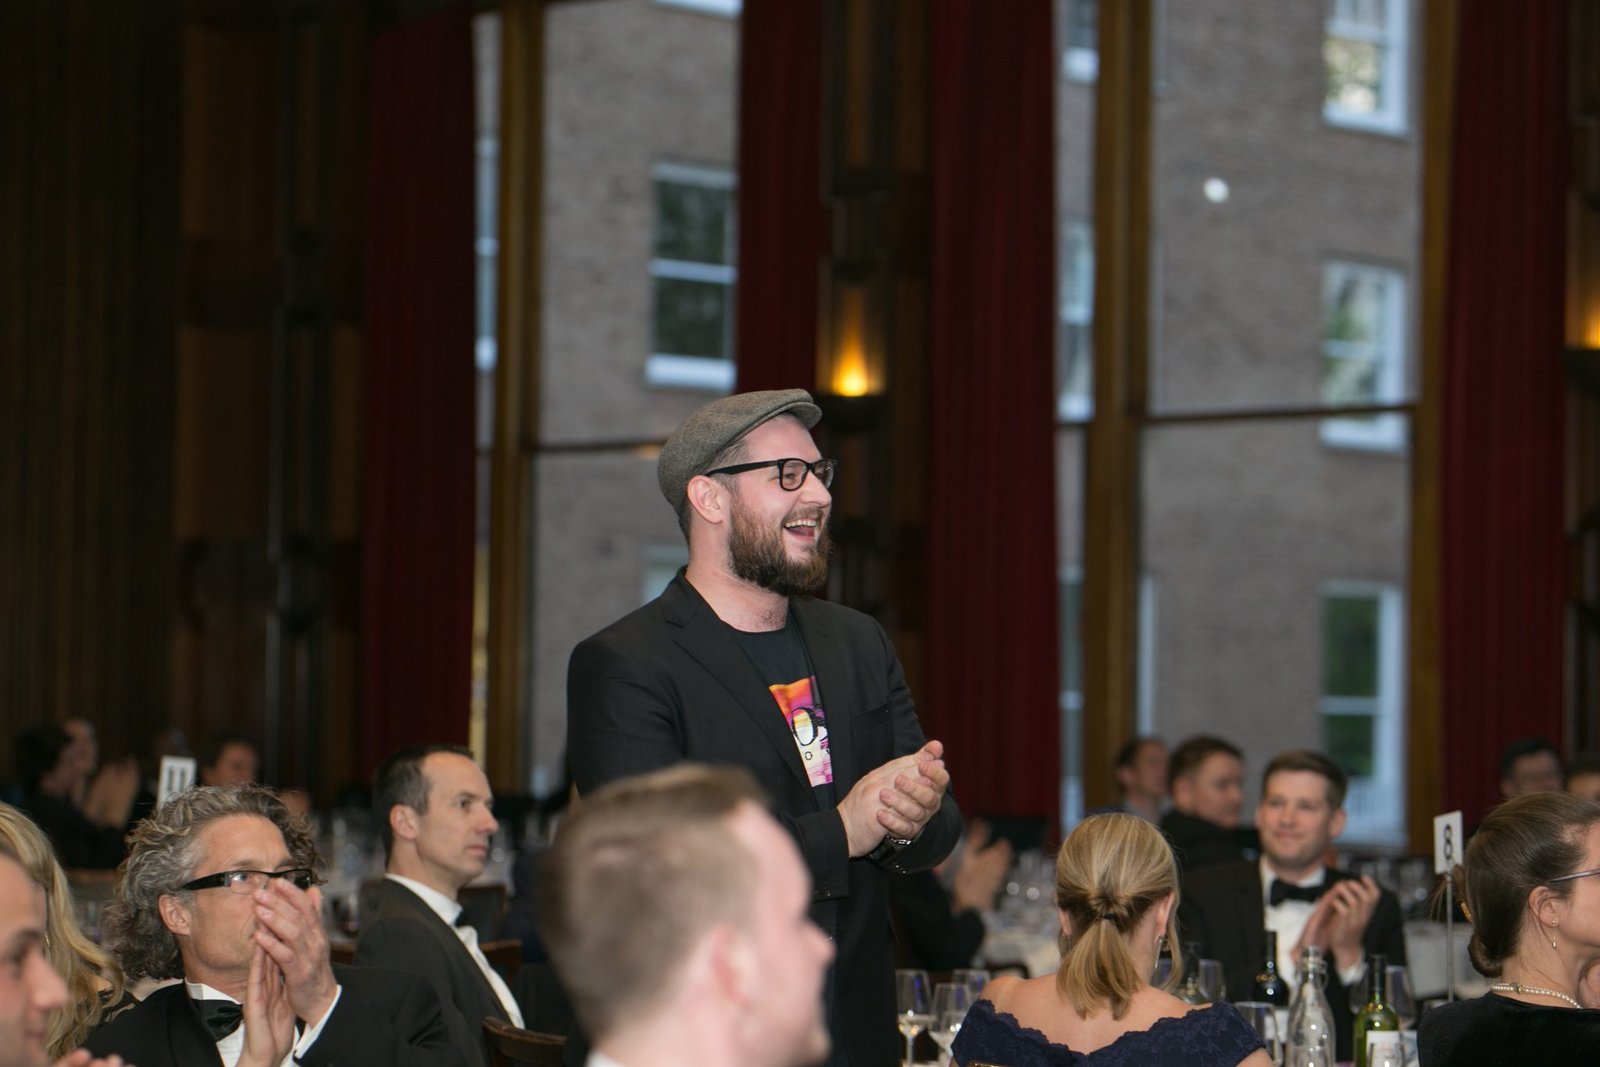
Featured image shows Josef Prusa at the 2018 3D Printing Industry Awards. Photo via 3D Printing Industry.
