
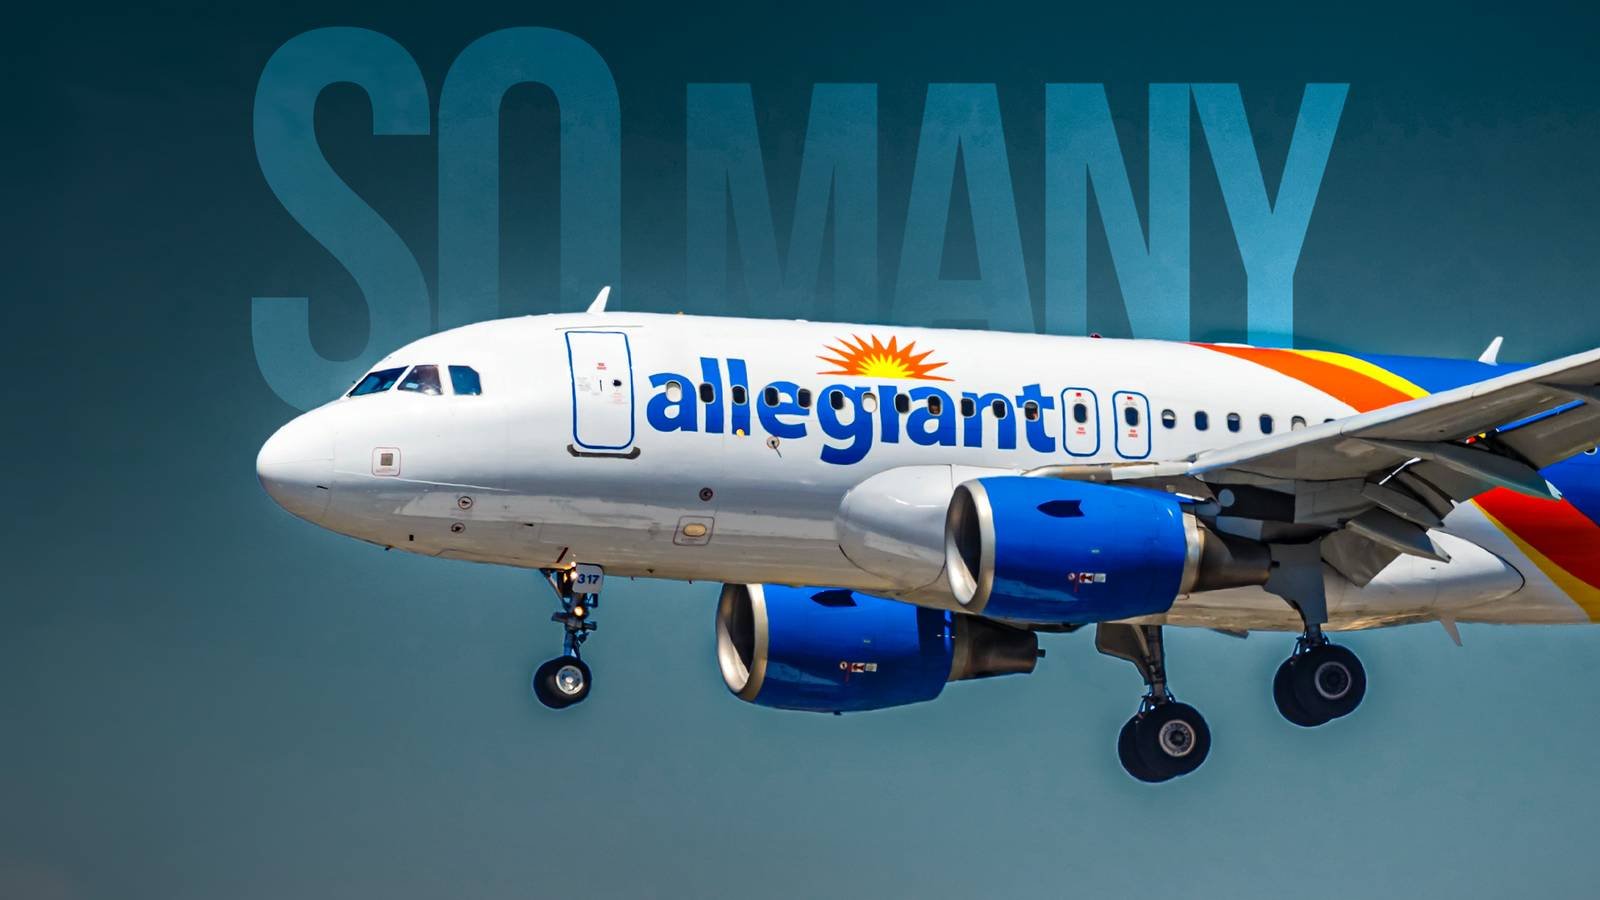
Where others have failed, Allegiant Air still stands strong as an ultra-low-cost carrier. Operating out of secondary hubs like Orlando Sanford International Airport (SFB) or St. Pete–Clearwater International Airport (PIE), many often assume the airline operates there for one important reason: rock-bottom airport landing fees. Lower gate charges and cheaper terminal operational costs certainly aid the bottom line, but that common perception misses the core meaning of the carrier’s business model.
Instead of taking passengers through crowded hub-and-spoke airports, Allegiant targets small and medium-sized cities, connecting local travelers directly to popular sun and vacation destinations with nonstop flights. Focusing on communities overlooked by major network carriers, the airline offers a compelling alternative to long drives or multi-leg connecting flights. As Allegiant emphasized during its 2025 network expansion announcements, serving secondary airports allows the carrier to build a resilient, low-frequency point-to-point network that stimulates brand-new passenger traffic rather than fighting for existing market share.
No Need For Major Hubs?
Reduced landing fees and lower gate lease rates are the most visible financial benefits of secondary airports, though this is only the foundation of Allegiant Air’s operational strategy. Airports like SFB, Phoenix-Mesa Gateway (AZA), and Chicago Rockford International Airport (RFD) provide an immediate cost floor that major hubs cannot match. However, the commercial strategy extends far deeper into market stimulation. As reported by The Points Guy, when Allegiant unveiled a major 30-route network expansion across 35 cities, the ultra-low-cost carrier focused heavily on underserved regional points such as Gulf Shores International Airport (GUF) in Alabama. With favorable fee structures at secondary facilities, the airline can enter small-to-midsize markets where legacy carriers cannot profitably operate, creating brand-new leisure traffic.
Secondary airports grant Allegiant unmatched operational efficiency through reduced congestion and shorter ground turnarounds. Operating away from congested airspace eliminates extended taxi times and holding patterns, directly lowering fuel burn. According to analysis from Simple Flying, Allegiant relies heavily on an out-and-back routing model where aircraft return to their home bases every evening. Secondary airports accommodate this structure seamlessly by offering quick gate turns and flexible slot availability, allowing flight crews to maximize flying hours without incurring costly outstation overnight accommodation fees or maintaining complex hub-and-spoke feed systems.
Catch what other flight trackers miss
Emergency squawks, holds, NOTAMs — live signals, no signup.
Open tracker
Catch what other flight trackers miss
Emergency squawks, holds, NOTAMs — live signals, no signup.
Open tracker
Crucially, secondary airports provide the structural freedom to align flight frequency directly with shifting leisure demand. Unlike network carriers bound to daily schedules by corporate travel requirements, Allegiant often serves secondary routes only two or three days a week during peak travel windows, as per Deep Arrival. Low fixed facility overhead means that aircraft can sit idle on ramp space during low-demand midweek days without incurring ruinous airport holding costs. As a result, Allegiant has made it surprisingly easy to use modest regional infrastructure for major success, showing that lower airport fees are simply the catalyst of point-to-point network dominance.
Showing Up Where Others Do Not

Legacy carrier consolidation over the past two decades left dozens of small and medium-sized American cities with dwindling air service options. As major network airlines pulled back regional jets and concentrated operations around massive hub airports, travelers in mid-market communities faced reduced flight schedules and escalating ticket prices. According to SEC filings and corporate network reports, Allegiant explicitly targets these underserved regions, such as Appleton, Wisconsin, and Columbia, Missouri, where legacy carriers abandoned direct leisure links in favor of hub-and-spoke feed systems.
Where the others left, Allegiant serves secondary origin markets directly and removes the long drive to a distant hub airport that often pains travelers. Prior to Allegiant’s entry, a traveler in a mid-sized city often had to drive over 100 miles (161 km) or accept a multi-leg itinerary just to reach a vacation spot. Now, those exhausting highway drives or tedious layovers are put to one side, keeping travel entirely local from departure to landing.
Allegiant’s convenience, paired with ultra-low base fares, opens up price-sensitive leisure demand that otherwise would remain untapped. In media statements accompanying recent network additions, Allegiant leadership emphasized that the airline’s mission centers on delivering nonstop access where vacation demand is strongest. By offering direct routes to important leisure hubs, Allegiant makes it possible for occasional travelers to be frequent vacationers.
A Four-Day Travel Window

Matching seat capacity to real-time leisure demand rather than maintaining rigid daily timetables forms the backbone of Allegiant’s operational philosophy. Legacy carriers have to operate multiple daily flights on major routes to capture lucrative corporate travel, but leisure travelers prioritize departure day and price over schedule density. What low-cost carriers do is schedule flights on an average of just two or three days a week so that they align their seats with peak vacation travel windows and avoid low-yield flights.
As per Simple Flying route analysis, the carrier concentrates flight frequencies around Thursday, Friday, Sunday, and Monday, when vacationers traditionally start and end their trips. Midweek days see aircraft parked on ramps at secondary bases like SFB and Punta Gorda (PGD). During periods of fuel price volatility, the carrier intentionally trims off-peak capacity to protect profitability, an adaptive strategy frequently highlighted in quarterly financial reports.
Financing aircraft through direct ownership or secondary market leases grants the airline the freedom to let planes sit idle during low-demand periods. Traditional network carriers face heavy daily capital costs on leased jets that force them to keep planes flying constantly, but Allegiant avoids this trap through a low-utilization model. The disciplined capacity matching is what prevents the carrier from flooding small cities with excess seats, keeping load factors high and protecting yields across its regional network.
Running Alone Without Competition

Legacy network airlines seem to always be deep into fare battles across major hub corridors like  Chicago O’Hare International Airport (ORD),
 Hartsfield-Jackson Atlanta International Airport (ATL), and
 Dallas/Fort Worth International Airport (DFW). Allegiant avoids these congested battlegrounds entirely, focusing instead on routes where it operates as the sole provider of non-stop air service. According to coverage from Simple Flying and The New York Times, the ultra-low-cost carrier faces no direct airport-pair competition on roughly 75% to 85% of its routes. The lack of competition gives Allegiant somewhat of a defensive moat around its network, protecting its pricing from the fare wars waged by the legacy carriers.
Structural cost disparities prevent major network carriers from mounting effective counter-attacks on these secondary routes. Major airlines rely on high-cost hub networks and regional jets to serve smaller communities, creating a Cost per Available Seat Mile (CASM) profile far too high to compete with low-fare mainline flights. According to airline fleet reports from ch-aviation, Allegiant deploys 177- to 186-seat Airbus A320 aircraft into low-cost secondary facilities, though as reported by Simple Flying, the airline is quickly adding Boeing 737 MAX aircraft into the fleet that feature 190 seats. A legacy carrier attempting to match Allegiant’s low fares on these point-to-point pairs would suffer unsustainable yield dilution across its regional feeder network.
Operating without direct non-stop competition also protects Allegiant’s lucrative unbundled revenue model. When major airlines introduced basic economy ticket tiers to combat ultra-low-cost carriers, those discounted fares targeted high-density hub routes instead of niche point-to-point corridors. SEC disclosures highlight that Allegiant consistently generates over $60 per passenger in ancillary revenue through add-ons like seat selection, checked bags, and priority boarding. Local travelers have no alternative non-stop option at their regional airport, so Allegiant retains total pricing power over these ancillary streams.
Local Demand Is Plenty

Establishing permanent operational bases at secondary airports forms a key structural advantage for Allegiant Air. Rather than staging aircraft exclusively at major hubs, the ultra-low-cost carrier maintains fixed crew bases at regional facilities across the country, including Grand Rapids, Des Moines, Flint, and Appleton. Staging pilots, flight attendants, and maintenance personnel locally supports an out-and-back scheduling model where aircraft return to their home station every night.
Secondary airport arrivals also drive Allegiant’s highly lucrative travel package ecosystem. Because regional gateways typically lack extensive public transit networks, leisure travelers almost universally need ground transportation and accommodations. Allegiant integrates rental car bookings and hotel partnerships directly into its booking platform, mainly through its partnership with Expedia, which adds substantial third-party commissions on every itinerary.
Allegiant shows no signs of abandoning its proven secondary airport philosophy as it expands its fleet. With new aircraft orders entering service, company leadership continues to evaluate even more unserved domestic routes that fit their operational criteria. Competing carriers can go and fight for market share at congested primary hubs, because Allegiant continues to double down on hyper-local demand.
The Airline To Watch Out For?

Secondary airports are far more than cost-saving alternative landing sites. These airports form the bedrock of Allegiant Air’s structural profitability. Low airport fees, coupled with zero direct competition on over 75% of its route network, allow the airline to maintain healthy margins while offering low base fares across all of its routes. Paired with an industry-leading ancillary revenue model that captures non-ticket spend through proprietary booking channels, the carrier has successfully made low-frequency, point-to-point regional routes become highly reliable profit drivers.
The disciplined focus on secondary markets protects the airline from detrimental hub congestion, volatile regional jet economics, and industry capacity shifts affecting major domestic carriers. As Allegiant modernizes its fleet through the induction of 737 MAX aircraft alongside its existing Airbus fleet, reduced unit costs will further bolster its competitive advantage. With more than 1,400 potential non-stop routes identified across smaller communities, the carrier is uniquely structured to capture untapped leisure demand without altering its fundamental operational framework.
